跳至主要內容
OpenAI

2026年5月15日

產品

ChatGPT 中全新的個人理財體驗

正在尋找財務解決方案嗎?

載入中…

2026 年 6 月 25 日更新:美國的 Plus 和 Pro 使用者現在可透過網頁版、iOS 和 Android 使用 ChatGPT 的個人理財功能。


今天,我們向美國的 Pro 使用者推出 ChatGPT 全新個人理財功能的預覽版。現在,你可以安全地連結金融帳戶,透過資訊主頁掌握資金流向,並向 ChatGPT 提問,取得符合自身財務狀況的回答。過程中,你隨時都能掌控自己的資料。我們先向少數使用者開放預覽版,從實際使用情況中汲取經驗、改善體驗,再審慎擴大開放範圍。

金錢幾乎影響生活的每個面向:我們住在哪裡、做出什麼決定、如何照顧所愛的人,以及我們想像的未來。 但在今天,管理財務往往意味著得把帳戶、應用程式、信用/金融卡、貸款和試算表拼湊起來,才能知道整體狀況。 即使如此,也仍可能難以看清全貌,或不知道下一步該怎麼做。

許多人早已開始向 ChatGPT 尋求協助:每月有超過 2 億人使用 ChatGPT⁠(在新視窗中開啟)編列預算、諮詢投資問題、比較不同選擇,以及規劃未來目標等。GPT‑5.5 的最新進展提升了 ChatGPT 的推理能力,讓 ChatGPT 更能處理個人理財中常見的複雜問題,並考量每個人的具體情況。

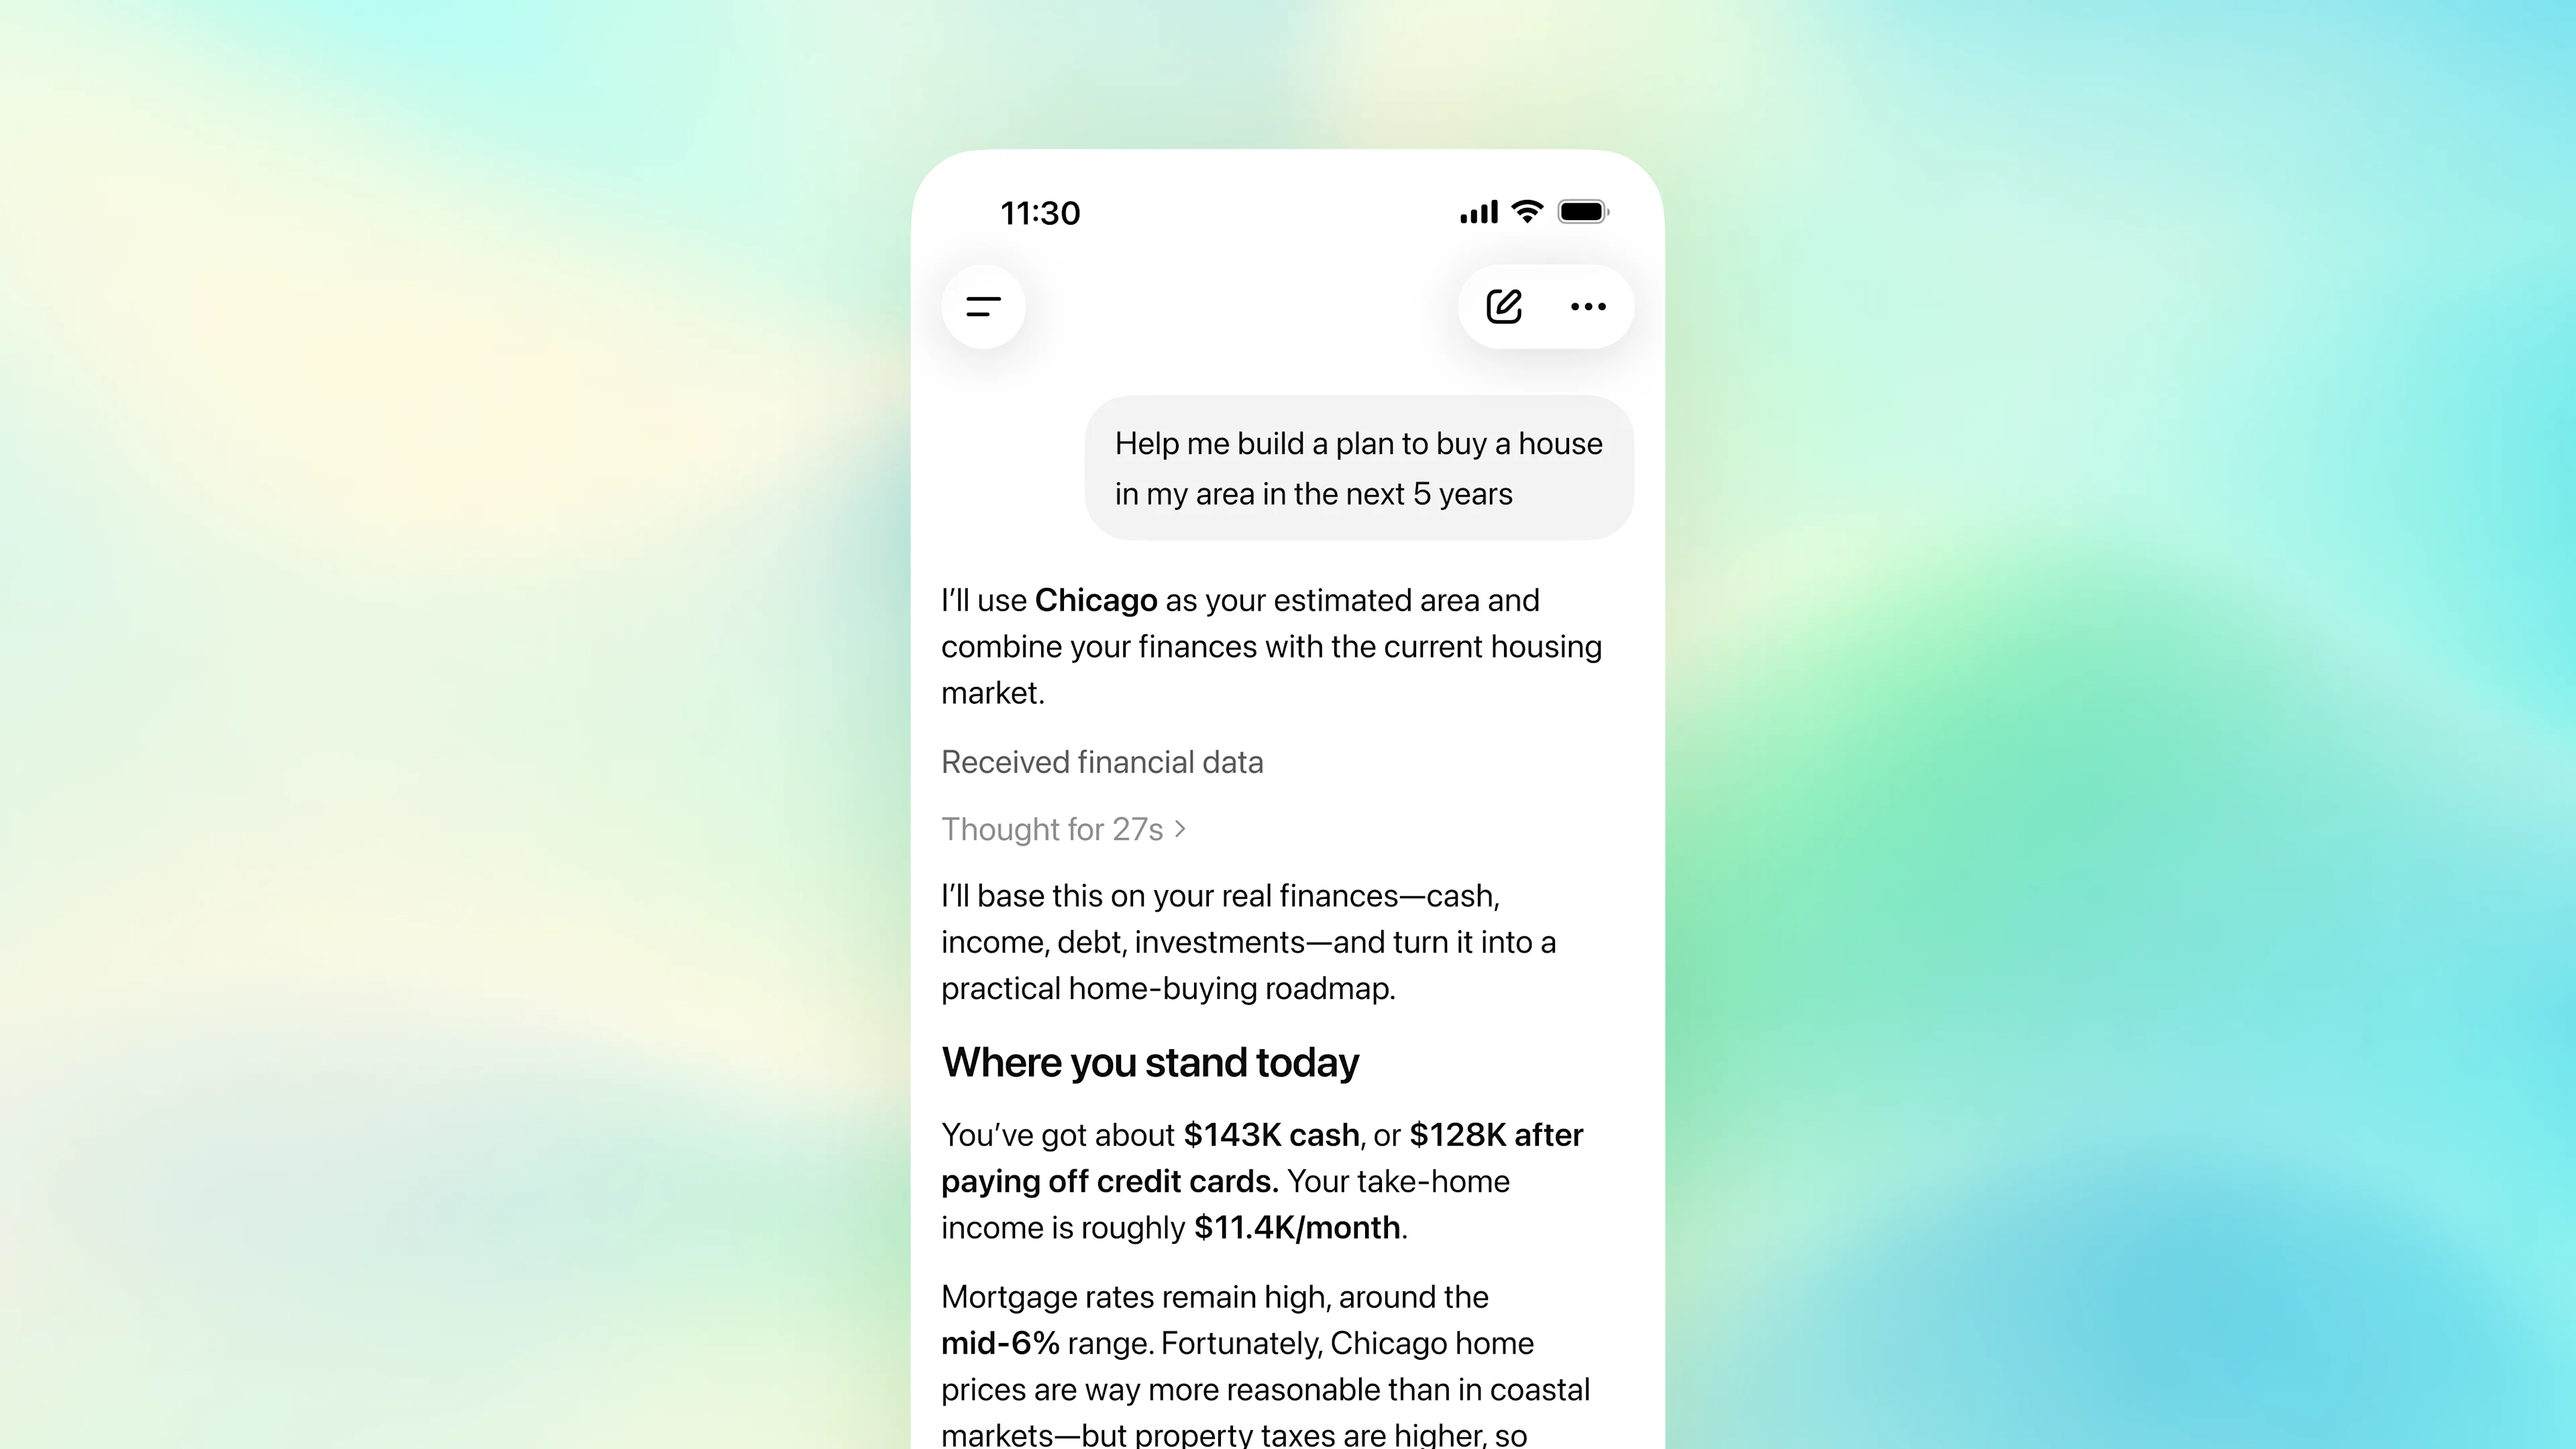
連接你的金融帳戶後,ChatGPT 能把這種推理能力與你的真實財務情境,以及你分享的目標、生活方式與優先事項結合,幫助你發現模式、理解取捨,並以更個人化且更完整的方式規劃重大決策。 現在你可以提出這類問題:

ChatGPT 可以幫助你掌握資訊,並更有信心地管理財務,但它不能取代專業財務建議。

從今天起,我們開始向美國的 Pro 用戶推出在網頁版與 iOS 版 ChatGPT 中連接金融帳戶的功能,支援超過 12,000 家金融機構。 在擴展到 Plus 之前,我們會先從早期使用中學習並持續改進,目標是最終讓所有人都能使用。

如何開始使用

連結你的財務資訊

若要開始使用,請從 ChatGPT 側邊欄開啟「財務」,然後選取「開始使用」。你也可以在 ChatGPT 的任何地方輸入「@財務,連結我的帳戶」來展開對話。

接著,ChatGPT 將引導你透過 Plaid 安全地連結帳戶,Intuit 支援也即將推出。你完成驗證後,ChatGPT 將開始同步並分類你的資料,這可能需要幾分鐘。
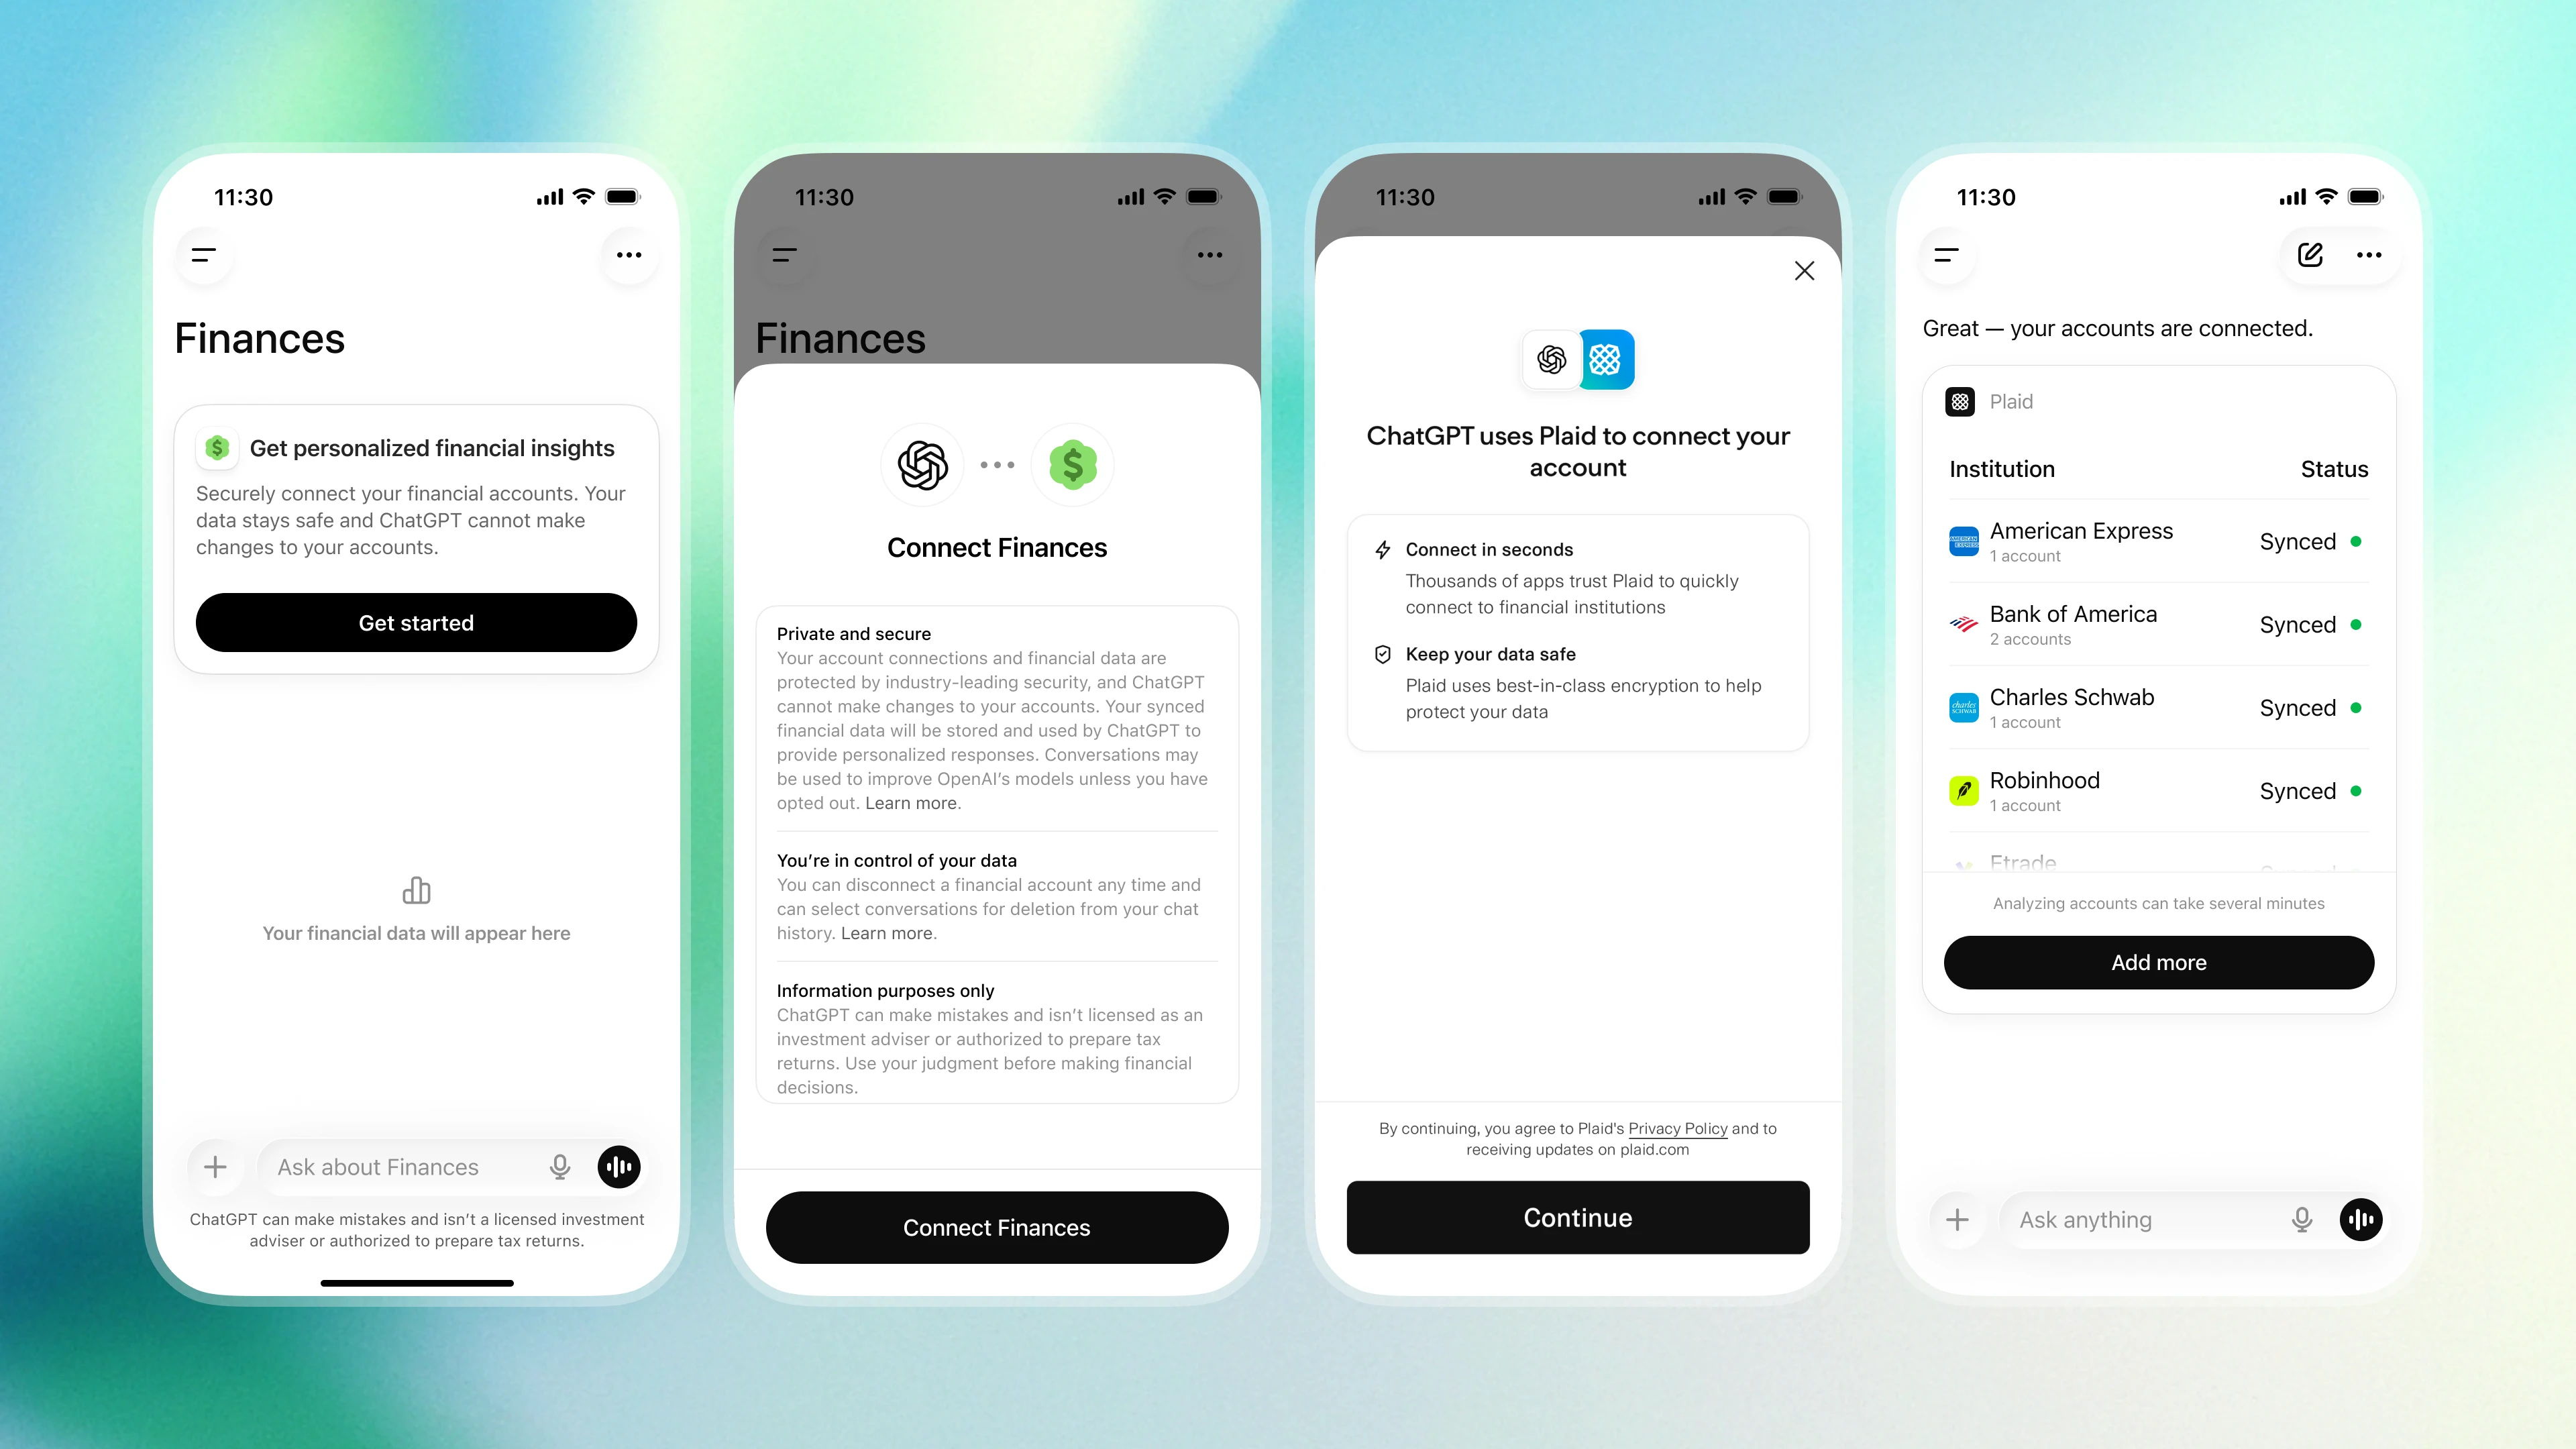
四個手機應用程式畫面,展示將金融帳戶連接到 ChatGPT 的流程

帳戶同步完成後,你可以查看總覽頁面,取得投資組合表現、支出、訂閱、即將到來的付款等最新整體狀況。

除了連結帳戶,你也可以補充重要的個人財務資訊,例如房貸、儲蓄目標,或計畫中的大額購物。例如,你可以告訴 ChatGPT:「我正在存錢,想在明年年初買車」,或「我向父母借的錢還有 [金額] 沒還」。ChatGPT 可以將相關資訊儲存為財務記憶,供日後對話參考。

這種更廣泛的背景正是此體驗實用的一部分,ChatGPT 不會把每個問題孤立看待,而是能幫你串連帳戶、目標與你已分享的資訊,讓建議更個人化也更完整。

未連接財務

Help me come up with a plan to save a little bit more in the next few months.

Here’s a practical way to save a bit more over the next 2–3 months without making your life miserable.

1. Pick a specific target

Make the goal concrete and time-bound.

Examples:

  • “Save an extra $1,500 by August.”

  • “Build a one-month emergency cushion.”

  • “Save enough for travel / taxes / moving / investing.”

A vague goal like “spend less” usually fades quickly.

2. Focus on the 3 highest-impact categories

Most people don’t need to optimize everything. Usually 70–80% of extra savings comes from a few categories:

Food & delivery

Good targets:

  • Reduce takeout from 5x/week → 2x/week

  • Bring coffee/lunch a few days per week

  • Set a fixed “fun food” budget

Even a small reduction here can free up a few hundred dollars monthly.

Subscriptions & recurring charges

Look for:

  • Duplicate streaming/services

  • Annual plans you forgot about

  • Apps you rarely use

  • Higher-tier plans you don’t need

A 20-minute cleanup can permanently lower monthly burn.

Impulse spending

Instead of “don’t buy stuff,” use friction:

  • 48-hour rule for purchases over a set amount

  • Remove saved cards from shopping apps

  • Keep a running wishlist instead of instant purchases

This cuts emotional purchases without feeling restrictive.

3. Automate the saving immediately

The biggest difference-maker is usually automation.

Try:

  • Automatic transfer every payday

  • Separate high-yield savings account

  • Move the money before you see it

Even:

  • $75/week = ~$900 in 3 months

  • $150/week = ~$1,800 in 3 months

Small consistent transfers beat occasional big efforts.

4. Create one “low-spend default”

Don’t try to optimize every decision.

Examples:

  • Weeknights = home-cooked meals

  • One no-spend day per week

  • Fixed entertainment budget

  • Only one convenience purchase category at a time

Simple rules reduce decision fatigue.

5. Increase income slightly instead of only cutting

For a short-term savings push, earning a little extra is often easier psychologically than aggressive budgeting.

Ideas:

  • Sell unused gear/clothes/electronics

  • Freelance or consulting work

  • Small weekend project

  • Negotiate a recurring expense (insurance, internet, phone)

Even an extra few hundred dollars changes momentum fast.

6. Track only one number weekly

Avoid overcomplicated budgeting systems.

Every week, check:

“How much did my savings increase this week?”

That keeps attention on progress rather than guilt.

A realistic “light effort” version

If you want something sustainable and low-stress:

Monthly

  • Cut 2–3 subscriptions

  • Reduce dining out modestly

  • Auto-transfer savings on payday

Weekly

  • One no-spend day

  • One meal-prep session

  • Quick 5-minute money check-in

That alone can often create an extra few hundred dollars/month without dramatic lifestyle changes.

If you want, I can also help you build:

  • a lean 3-month savings plan,

  • a category-by-category budget,

  • or a “minimal pain” version based on your current spending habits.

已連接財務

@Finances Help me come up with a plan to save a little bit more in the next few months.

I’ll look at recent spending, recurring charges, and cash-flow patterns, then turn that into a practical “save a little more” plan rather than a harsh budget.

按支出類別制定的省錢計劃

Here’s the plan I’d use for the next few months. May is still early, so I’m anchoring this mostly on February–April plus the May-to-date spending.

At a $110K salary, the goal is not to make life feel overly restricted. It’s to create more consistency across normal spending categories so saving happens before the month gets away from you.

Your biggest flexible spending levers recently are:

項目

2 月 1 日–5 月 9 日支出

代表意義

雜貨與家庭用品

~$2,150

屬正常範圍,但值得用每週目標再收緊一些

購物

~$1,250

很有改善空間,尤其是 Target/Amazon/服飾採買

交通

~$1,450

油費、停車、叫車與汽車成本累積可觀

餐飲與飲品

~$1,620

非常適合著手調整,且不必完全砍掉

訂閱與帳單

~$420

金額不大,但容易清理

Target: save an extra $500–$750/month

I would not start by trying to eliminate every small pleasure. Your biggest wins are dining, shopping, transportation, and grocery pacing.

1. Dining: cap at $450/month

Dining has been one of the easiest places for spending to drift. I’d set a realistic cap of $450/month, which still leaves room for takeout, coffee, and a few meals out.

Expected savings: $150–$250/month.

Use a simple rule: pick 2–3 meals out per week, then default to groceries for the rest.

2. Shopping: cap at $300/month

Shopping is not extreme, but it’s the kind of category that can quietly turn into $500–$700 months through Amazon, Target, clothes, and household extras. I’d set a $300/month cap through August.

Expected savings: $150–$250/month.

Use a simple rule: anything over $75 waits 24 hours before buying.

3. Transportation: set a monthly ceiling

Between gas, parking, car maintenance, and occasional rideshare, transportation can become a bigger budget item than it feels in the moment. I’d set a $400/month transportation target, excluding true emergencies or required repairs.

Expected savings: $100–$200/month.

The rule I’d use: rideshare is for late nights, bad weather, carrying things, or when it saves 25+ minutes. Otherwise default to driving, walking, transit, or planning ahead.

4. Groceries: use a weekly target, not a strict diet

Groceries and household basics are necessary, so I wouldn’t treat this as “bad spending.” But I would set a weekly grocery target of about $125–$150 and try to avoid extra midweek convenience runs.

Expected savings: $100–$150/month.

5. Subscriptions: small cleanup only

The recurring charges are not where the big money is, but they’re still worth checking: streaming, apps, news, fitness, cloud storage, and memberships. Canceling one or two might save $20–$50/month. Useful, but not the main plan.

The monthly savings formula
For June–August:

可調整項目

每月目標

餐飲上限

+ $200

購物上限

+ $200

交通上限

+ $150

雜貨支出控管

+ $125

訂閱清理

+ $30

預估可節省總額

~$705/月

To make it stick, I’d automate $500/month to savings first. Then treat the extra $200–$250 as the stretch goal when dining, shopping, or transportation comes in lighter.

Best version of the plan: auto-save $500/month, cap dining at $450, cap shopping at $300, set a transportation ceiling, and use weekly grocery targets so the plan feels realistic instead of restrictive.

從回答走向行動,攜手 Intuit 等生態系夥伴

ChatGPT 的願景不只是回答問題,更要幫助用戶採取行動、改善財務生活,而我們正與 Intuit 等值得信賴的生態系夥伴合作實現這一點。 例如,用戶可以從獲得信用卡推薦,進一步了解自己的核准機率並提交申請;或從詢問賣出股票的稅務影響,進一步取得可信的稅額估算並預約與在地真人稅務專家的諮詢,這些都由 Intuit 提供支援,且全都在 ChatGPT 內完成。

保護你的資訊隱私與安全

你的財務資料相當敏感,我們打造這項體驗時,特別重視你的隱私,並確保你能掌控自己的資訊。

連結帳戶後,ChatGPT 可以存取你的餘額、交易、投資與負債資訊,協助你將財務狀況以圖表呈現,或回答你的問題。ChatGPT 無法查看完整帳號,也無法對你的帳戶進行任何變更。

使用已連結金融帳戶資料的對話,會沿用你在 ChatGPT 中選擇的模型訓練設定。你可以隨時前往「設定 > 資料控管」⁠(在新視窗中開啟)變更此設定。

你的資訊始終由你掌控:

  • 中斷帳戶連結:你可以隨時前往「設定 > 應用程式 > 財務」,或從「財務」頁面中斷金融帳戶連結。中斷連結後,已同步的帳戶資料會在 30 天內從 OpenAI 的系統中刪除。中斷帳戶連結不會影響 ChatGPT 對話記錄中的財務資訊,但你可以隨時刪除個別對話。

  • 刪除財務記憶:ChatGPT 可以記住你分享的重要資訊,例如理財目標、需履行的財務責任或財務背景,讓日後在 ChatGPT 中進行的理財對話更切合你的需求與個人情況。相關資訊會儲存為「財務記憶」,專供財務相關對話參考。你可以隨時從「財務」頁面查看或刪除財務記憶。

  • 暫時對話:當你使用暫時對話時,ChatGPT 不會存取你已連接的金融帳戶。 臨時聊天不會顯示在你的歷史記錄中。

若要進一步保護你的 ChatGPT 帳戶,你可以啟用多重驗證機制 (MFA)⁠(在新視窗中開啟),多加一層保護,協助防止未經授權的存取。

為準確性與品質而設計並評估

使用已連結金融帳戶資料的對話,預設會使用 GPT‑5.5 Thinking⁠,這是我們在 ChatGPT 中推出的最新推理模型。

財務問題往往複雜、涉及個人情況,而且必須考量具體背景。要提供有幫助的回答,就必須考量個人的收入、支出、餘額、債務、目標與時間安排,同時清楚交代不確定之處、採用的假設,以及何時需要更多資訊。

為了更了解 ChatGPT 在這類情境中的表現,我們建立了一套內部基準,依據與專家共同制定的標準,全面評估回應品質。 我們與來自頂尖機構的 50 多位金融專業人士合作,評估這項體驗,並為 ChatGPT 在具挑戰性的個人理財任務上的表現評分。

GPT‑5.5 Thinking 在複雜的個人理財任務上優於較早期的模型。 提供給 ChatGPT Pro 用戶的 GPT‑5.5 Pro,達成了整體最佳表現。

* 個人理財基準分數,涵蓋具挑戰性的理財任務。這是由專家評分的回應品質與回應準確性加權組成的綜合分數;越高越好。財務的預設模型 GPT‑5.5 Thinking 在此基準測試中獲得 79 分,滿分為 100 分。GPT‑5.5 Pro 獲得 82.5 分,滿分為 100 分。

這項基準讓我們能更清楚衡量進展,而我們也會持續改善 ChatGPT 隨時間處理複雜個人理財任務的能力。
我們的 ChatGPT Pro 社群測試者怎麼說

作者

OpenAI